I just lived through a lesson I set in motion over the past two decades, and I think it is worth writing down while it is fresh: how you structure retirement money, and what happens when the structure you picked meets the exit you actually take.
How the money actually arrives
Start with the standard ways a company pays you. Base salary. Bonus. Many companies add stock: incentive plans, employee stock purchase plans. And then there is the leverage layer on top: retirement accounts, and for some of us, deferred compensation.
Deferred comp is a simple premise. Take some of today’s dollars, put them into investments pre-tax, let them grow, and have them paid back to you in the future, when you are theoretically in a lower tax bracket. That last part is key to the whole concept. And you choose the schedule for that payback: all of it when you leave the company, staggered in multiple ways, on a specific date, or any combination. And you typically reset those payback parameters at each years renewal.
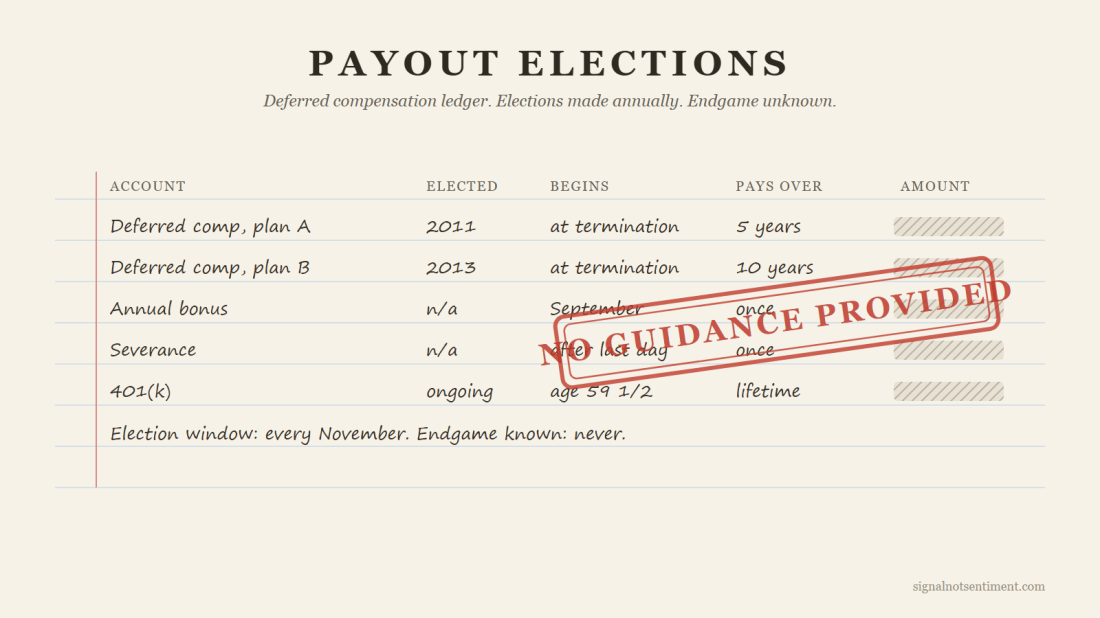
Here is the catch. There is no guidance on how to make that choice. Unless you go talk to a financial analyst, and many of us either don’t have access, choose not to, or don’t believe they have our best interests in mind, you work it out on your own. Your employer won’t take on the liability of giving you guidance, so that’s not an option. So you make a decision with the best information you have, which is close to none, because the decision is about an ending you cannot see yet.
The choice you make blind
Here is what I picked, as an example. Some of my deferred comp pays out over five years starting at termination. Some pays out over ten. I did not have any structure or thinking in mind beyond one instinct: it didn’t seem right that I would retire and all of the sudden need all of that money. If this is supposed to be a tax optimization strategy, taking it all at once defeats the point. So: five-year and ten-year streams, starting right after I leave, seemed like a good model. And honestly, the difference between five-year and ten-year payouts was more because I couldn’t remember what I had done the year before rather than anything intentional
It’s all kind of a crapshoot, because you don’t actually know any of the key facts when you are setting it up. You don’t know the year you will leave the employer, let alone the month. You don’t know if you’ll be moving to a new job or retiring or desperately hunting for a job. And you don’t know what events cause you to leave the job, and if those events carry financial needs or impacts. It turns out, all of this does matter.
The year everything paid out at once
I left Microsoft in September. Here’s an example to think through.
Eight and a half months of salary, because most of the year was already worked. A severance payment, landing after the last day. The annual bonus, if you are smart enough to time separation right after the qualification date. Then in October, the deferred compensation starts, all streams, per the schedules I set up over the past two decades.
What this means for me is that between September and October, I am collecting more paychecks than I would in a standard working year. This impacts taxes and tax brackets. Next year will be, at least at this point, significantly lower. Which is backwards from concept of deferred comp.
Let me be careful here, because this is totally a first-world problem. A lot of people right now are worried about their jobs, their families, and how to pay for groceries, and “my payouts stacked up” is not a hardship. It is definitely better than not getting paid, or getting paid less than your worth. But the mechanics are worth understanding precisely because nobody explains them to you when the choices are in front of you.
Had I known the ending back when I set this up, I would have structured it differently: deferred comp starting at termination plus four to six months, which would have pushed those streams into the lower-bracket year. Or I could have slid my last day to January and let everything land in the next calendar year. And knowing that a September exit is actually the natural shape for a lot of careers, since it sits right after the bonus and rewards cycle, I could have guessed better than I did.
But I will take the tax burden as the price of the extra three or four months of not having to work. I am happy with the date. And there is an honest counterweight to all this second-guessing: you might not leave on your own terms. If you get walked out in a layoff, having your deferred comp start immediately might be exactly the right structure. The schedule that is tax-inefficient for a planned retirement could be a lifeline for an unplanned one. You are choosing blind for both cases at once.
Every October for the next decade
One more artifact of that decades-old choice: some of my deferred comp pays out at the start of October, every October, for the next ten years. It is not a huge amount of money. But there it is, a small annual deposit from a decision made in a different life, arriving like a letter I mailed to myself from a lifetime ago.
The Gary problem
Two other cases to consider.
A friend of mine is working out his retirement date right now, and he has close to 100% of his salary going into deferred comp. For him, the month or quarter he picks genuinely matters. The structure is intentional.
And then there is my old buddy Gary. Years ago, Gary was convinced he would retire at 45 because he and his wife were living cheap and saving hard, which is a wonderful idea. But they almost exclusively poured that savings into their 401ks. Retirement accounts are not penalty-free until 59 and a half (the IRS rule), and the main exception, the Rule of 55, only opens your current employer’s 401k if you keep working there into the year you turn 55. Retire at 45 with everything in a 401k and you have built a nest egg you can watch compound for fourteen years and cannot spend. Hey bud, what exactly is the plan for years one through fourteen?
The pattern
Zoom out and there is a whole matrix here: Roth and standard retirement accounts, deferred comp, standard comp, severance, bonus, stock awards and grants. When each one pays, what each one costs in taxes, how centralized or diversified the whole picture is. Every one of those is a choice you make years before you know the story you are choosing for, and they all come together in the same few months at the end.
I made my choices with the best information I had at the time, and I am living with repercussions that are, honestly, pretty gentle. But the pattern deserves better than hope. None of this is advice; it is scar tissue with a structure in it, and the structure is worth mapping before your own October comes around. So put some thought into the following: (1) how and when your retirement accounts pay out, (2) how and when, across the tax year, you would optimally control your retirement date, (3) what your immediate versus delayed plans are for what you are going to do once you leave your job.
I’m no expert, but for people that are making decisions now from the other side of the equation I’m happy to have a conversation about what I would do the same, and what I might do different.